What SafetyWing Does Not Cover in Mexico: The Exclusion List, Line by Line
Navigating healthcare in a foreign country is one of the biggest headaches we expats face, and understanding insurance policies – especially what they don't cover – can feel like trying to decipher ancient hieroglyphics. Many of us arrive in Mexico as digital nomads or long-term travelers, often relying on popular travel medical insurance like SafetyWing. This guide is here to shed light on SafetyWing’s specific exclusions so you can avoid nasty surprises and plan your healthcare strategy in Mexico wisely.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Why Understanding Exclusions Is Crucial And Frustrating In Mexico
Believe me, I’ve been there. You’ve just landed, you’re caught up in the excitement of a new culture, and the last thing you want to do is pore over insurance documents. But ignoring the fine print, particularly the exclusions, can turn a minor mishap into a major financial disaster. In Mexico, where healthcare standards vary wildly and costs in private hospitals can be comparable to, or even exceed, those back home for complex procedures, knowing your coverage limits is not just smart—it’s essential.
The Reality of Healthcare Costs Without Coverage
Let’s be real: Mexico offers fantastic medical care, especially in its private hospitals, but that quality comes at a price. Without proper coverage, a simple emergency can quickly drain your savings. Imagine you’re enjoying a hike near Ajijic, trip and fall, and end up needing an X-ray and stitches. In a private clinic, that’s easily a few thousand pesos. Now, scale that up. A bad bout of appendicitis requiring surgery can easily hit six figures in pesos. I've known friends who faced truly shocking bills, well over $10,000 USD, for unexpected surgeries because they hadn't fully grasped their coverage limitations.
This isn’t to scare you, but to highlight that while Mexico might be more affordable for day-to-day living, major medical events can be just as expensive as anywhere else. That's why having a good base like SafetyWing is so crucial, but understanding its boundaries is equally important. For a broader perspective on the system, check out our guide on Healthcare in Mexico: Complete Guide for Expats (Public vs Private).
Navigating the System: What Expats Often Miss
One of the biggest pitfalls for expats is assuming their travel medical insurance acts like comprehensive health insurance from their home country. It doesn't. Travel medical plans, including SafetyWing, are designed primarily for unforeseen medical emergencies and catastrophic events when you're away from your home country. They're fantastic for what they do, providing that critical safety net, but they're not typically built for routine care, managing chronic conditions, or elective procedures.
This distinction is huge. It means if you wake up with a nasty ear infection, SafetyWing will likely cover the urgent doctor's visit and antibiotics, because that's an acute, unexpected illness. But if you're due for your annual physical or want to get some cosmetic dental work done, that's almost certainly on you. Many expats learn this the hard way, thinking they're fully covered only to find out their policy doesn't cover what they expected. This leads to frustrating out-of-pocket expenses and a lot of confusion, especially when there’s a language barrier at play.
SafetyWing's General Exclusions: What You Absolutely Need to Know
SafetyWing's Nomad Insurance is a lifesaver for many digital nomads and long-term travelers in Mexico. It provides robust emergency medical coverage, travel interruption, and even emergency dental and vision due to accidents. However, like all insurance, it has its limits. Understanding these exclusions isn't about finding fault with SafetyWing; it's about being a prepared expat. Let's break down some of the key things SafetyWing generally does not cover.
Pre-Existing Conditions: The Big One
This is probably the most common point of confusion and frustration for expats. A "pre-existing condition" generally refers to any illness, injury, or medical condition for which you've had symptoms, received treatment, or been diagnosed before your policy's effective date.
SafetyWing, for its standard Nomad Insurance, typically does not cover expenses related to pre-existing conditions. This means if you have diabetes, high blood pressure, asthma, or a recurring back issue that flared up before you bought the policy or during its waiting period, medical care related to these conditions will not be covered.
However, there's a crucial nuance: SafetyWing may cover the acute onset of a pre-existing condition, but this coverage is often limited to a certain amount (e.g., up to $25,000 or $50,000 for those under 65, and typically only up to age 65) and only if it requires immediate medical treatment to avoid severe harm or death, and you sought treatment within a specific timeframe after the onset. This limited acute onset coverage is a lifesaver for sudden, severe exacerbations, but it's not for routine management or flare-ups that don't meet the "acute onset" definition.
For expats moving to Mexico with known medical issues, this is a huge consideration. You'll need to explore other options for managing your chronic conditions. Dive deeper into this topic with our guide on Pre-Existing Conditions: Will Mexican Health Insurance Cover You?.
Routine Care, Screenings, and Elective Procedures
This category covers the vast majority of non-emergency healthcare you might seek out in Mexico. SafetyWing's Nomad Insurance is designed for unexpected medical events, not for your regular health maintenance.
- Routine Physical Examinations: Your annual check-up, blood work, and general health screenings are not covered. If you want to get an annual physical from an English-Speaking Doctor in Mexico, you'll pay out-of-pocket.
- Preventive Care: Vaccinations, mammograms, colonoscopies, pap smears, and other preventive screenings are generally excluded.
- Elective Treatments and Cosmetic Procedures: Any surgery or treatment performed purely for aesthetic reasons, or chosen for convenience rather than medical necessity (e.g., getting a tummy tuck, teeth whitening, or non-emergency dental work like crowns or orthodontics), falls outside of coverage. While Mexico is popular for medical tourism for these very reasons, SafetyWing won't cover them. This also extends to vision correction surgeries like LASIK.
- Non-Emergency Dental and Vision: While SafetyWing does cover emergency dental treatment due to an accident (e.g., you fall and break a tooth), it does not cover routine dental cleanings, fillings, root canals, or prescription eyeglasses/contact lenses. If you're planning on getting affordable Dental Care in Mexico: Quality of Service and Costs for Expats, budget for it yourself. The same goes for regular eye exams and new glasses.
Mental Health Limitations
Mental health is a critical aspect of overall well-being, especially when navigating the stresses of expat life. While awareness is growing, many travel medical insurance policies still have limitations here, and SafetyWing is no exception.
SafetyWing's Nomad Insurance may offer limited coverage for acute psychiatric crises that require hospitalization. However, it typically does not cover routine therapy sessions, ongoing counseling, or treatment for non-acute mental health conditions. If you're seeing a therapist for anxiety, depression, or adjustment issues, those sessions will almost certainly be an out-of-pocket expense. This is an area where expats often need to seek out local resources and pay directly. It's worth researching Mental Health Resources: Finding English-Speaking Therapists in Mexico if this is a concern for you.
High-Risk Activities and Extreme Sports
Mexico is an adventurer's paradise, offering everything from diving in cenotes to surfing on the Pacific coast, climbing volcanoes, and ATV tours through jungles. It's exhilarating! But if you're planning on pushing your limits, be aware of insurance exclusions.
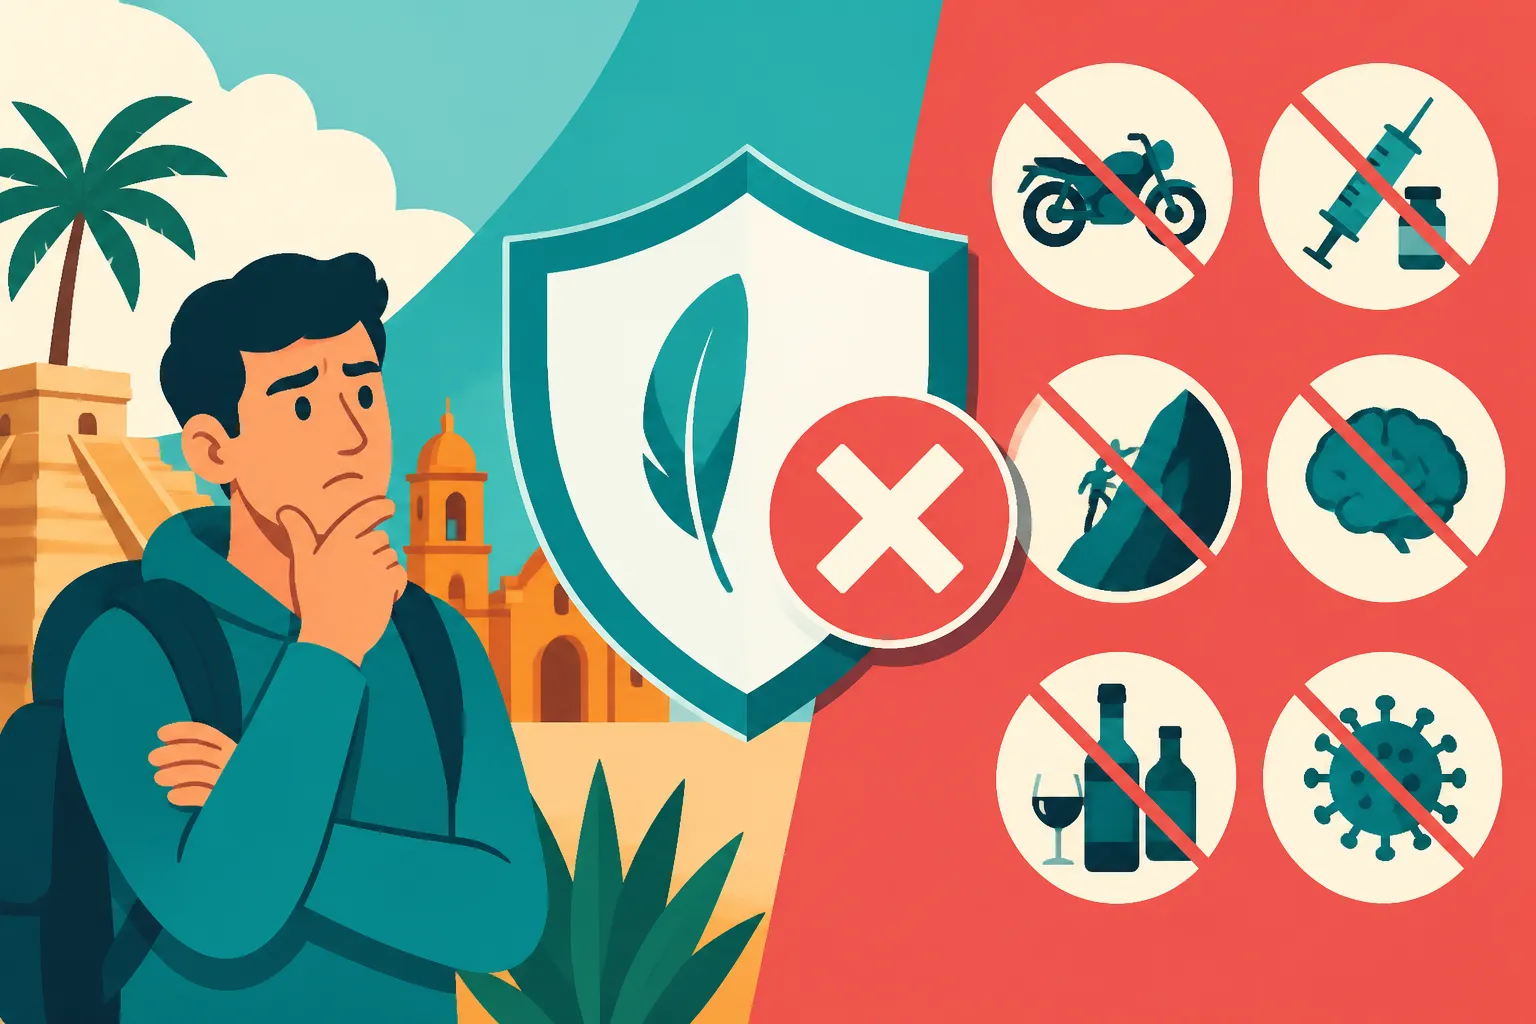
SafetyWing generally does not cover injuries sustained while participating in professional sports, dangerous or extreme sports, or other high-risk activities that are explicitly excluded in their policy wording. While regular recreational activities like swimming or hiking are typically fine, things like skydiving, free solo climbing, or organized competitive sports may be excluded. Always check the specific policy document for a list of excluded activities. If your passion involves something potentially risky, you might need specialized adventure sports travel insurance or an add-on.
Alcohol, Drugs, and Self-Inflicted Injuries
These are fairly standard exclusions across most insurance policies, and SafetyWing is no different. You won't be covered for medical expenses arising from:
- Alcohol or Drug Abuse: If you injure yourself or require medical attention due to being under the influence of alcohol or non-prescription drugs, SafetyWing will generally not cover the costs.
- Self-Inflicted Injury/Suicide: Any medical care related to intentionally harming yourself or suicide attempts is excluded.
- Illegal Acts: If you're involved in illegal activities and get injured as a result, your medical costs won't be covered.
Travel to Home Country and Other Exclusions
SafetyWing Nomad Insurance is designed for your travels outside your home country. While it does offer some incidental home country coverage (e.g., short visits back home), typically for every 90 days of coverage you accumulate, you get 30 days of coverage in your home country (15 days if you're in the US). However, this is for acute onset of new conditions that occur during that limited period. It's not meant for ongoing care or seeking treatment for issues that arose while abroad.
Other less common but important exclusions to be aware of include:
- Acts of War or Civil Unrest: While generally safe, if you're in a region experiencing war, rebellion, or civil unrest and get injured, coverage might be excluded.
- Nuclear, Chemical, or Biological Contamination: Illness or injury resulting from these types of events is typically not covered.
It’s absolutely vital to read the full policy document when you purchase SafetyWing or any other insurance. The information here is a general overview, and specific terms and conditions can change or vary.
When to Consider Additional Coverage or Alternatives in Mexico
Understanding what SafetyWing doesn't cover isn't a knock against the product; it's a call to proactive planning. SafetyWing is a fantastic and affordable solution for emergency travel medical insurance, perfectly suited for the nomadic lifestyle and the unexpected medical emergencies in Mexico. But for those settling in for the long haul, or with specific health needs, you might need to layer your coverage. For an in-depth comparison of options, read our guide on Health Insurance in Mexico: How Expats Can Get Coverage (2027).
Filling the Gaps: Local Insurance and Specialized Plans
If you're planning to make Mexico your long-term home, or if you have specific health needs that fall outside SafetyWing's emergency-focused coverage, it's time to look at other options. Many expats choose to supplement or even replace their travel medical insurance with local plans.
- Local Mexican Health Insurance: Companies like GNP Seguros, AXA Seguros, and Qualitas offer comprehensive health insurance policies designed for residents in Mexico. These plans often cover routine care, specialists, and sometimes even pre-existing conditions (though usually with waiting periods and higher premiums). They also simplify direct billing with local hospitals, which can be a huge relief during a medical emergency. They understand the local system and often have better networks within Mexico. This is a great alternative if you need more than emergency coverage, but expect higher costs than SafetyWing. You may also want to compare with Choosing Private Health Insurance: Local Mexican Plans vs International Coverage.
- International Health Insurance: For those who travel frequently or want comprehensive coverage that extends beyond Mexico and potentially back to their home country (with varying limitations), international health insurance providers like Cigna Global or IMG offer robust plans. These are often more expensive but provide extensive coverage, including routine check-ups, specialist visits, and sometimes even dental and vision add-ons. They're a good fit if you need high-level, flexible coverage.
- IMSS (Public Healthcare): If you have a Temporary or Permanent Resident visa and are legally employed in Mexico, or choose to enroll voluntarily, you might qualify for IMSS. While it has its own set of challenges, including wait times and language barriers, it provides extremely affordable (or free) comprehensive healthcare. However, IMSS usually has waiting periods for pre-existing conditions and often lacks the amenities of private hospitals. You can learn more about this by reading Public Healthcare in Mexico: IMSS and IMSS Bienestar Explained for Expats.
Specific Scenarios: Chronic Conditions and Planned Procedures
This is where your healthcare strategy really comes into play. If you live with a chronic illness, SafetyWing will not be your long-term solution. You'll need to research local insurance options that are willing to cover your specific condition, or budget significantly for out-of-pocket expenses for ongoing medication, specialist visits, and tests. You'll definitely want to understand Managing Chronic Illness in Mexico: Access to Medication and Specialists.
Similarly, if you're planning a non-emergency surgery or a major dental procedure, you'll need to pay for it directly or ensure you have a local or international comprehensive plan that explicitly covers such treatments. Don't rely on SafetyWing for these planned, non-emergent medical events.
Emergency Evacuation: An Essential Consideration
While this article focuses on exclusions, it's important to highlight a critical feature that SafetyWing does cover and that every expat in Mexico should prioritize: emergency medical evacuation. Mexico is a large country with diverse healthcare infrastructure. While major cities like Mexico City, Guadalajara, and Monterrey have world-class hospitals, smaller towns and rural areas might not.
If you have a severe medical emergency in a remote part of Oaxaca or a small pueblo in Chiapas, being able to be medically evacuated to a facility that can provide the necessary care (even to your home country in extreme cases) is literally life-saving. SafetyWing's inclusion of emergency medical evacuation is a huge benefit and often a reason why many expats choose it as their baseline. It's truly a non-negotiable for anyone living away from advanced medical hubs. Don't underestimate the importance of this, especially if you're in Emergency Medical Services in Rural Mexico: Challenges and Tips for Expats.
Here’s a quick overview of common exclusions and how they might affect you in Mexico:
| Category | SafetyWing Nomad Insurance Coverage | Impact for Expats in Mexico |
|---|---|---|
| Pre-Existing Conditions | Generally excluded, limited acute onset coverage. | Major out-of-pocket risk for chronic illnesses. Look into local plans. |
| Routine Check-ups | Excluded | Annual physicals, screenings, and preventive care are self-pay. |
| Elective Procedures | Excluded | Cosmetic surgery, non-emergency dental work, vision correction are self-pay. |
| Routine Dental Care | Excluded (except for accident) | Cleanings, fillings, orthodontics require out-of-pocket payment. |
| Routine Vision Care | Excluded (except for accident) | Eye exams, glasses, contacts require out-of-pocket payment. |
| Mental Health (Non-Acute) | Limited to acute crisis requiring hospitalization | Ongoing therapy or counseling are usually self-pay. |
| High-Risk Sports | Excluded (check policy for specifics) | Adventure activities may not be covered if not recreational. |
| Alcohol/Drug Related Incidents | Excluded | Injuries or illness under the influence are not covered. |
| Home Country Treatment | Limited incidental coverage | Not for extended care or seeking treatment for issues that arose abroad. |
Ultimately, SafetyWing is an excellent foundation for your healthcare safety net in Mexico, particularly for unexpected emergencies and catastrophic events. It’s designed for flexibility, affordability, and the specific needs of digital nomads. However, it's not a substitute for comprehensive long-term health insurance. For many expats, the smart move is to use SafetyWing for its core strengths while either self-insuring for routine care or investing in a local Mexican plan to cover those additional needs.
Before you make any decisions, get a quote from SafetyWing to understand your potential coverage and always, always read their full policy documentation. Knowledge is power, especially when it comes to your health and finances abroad!
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, legal, or medical advice. Insurance policies and terms can change, and individual circumstances vary. Always consult with a qualified insurance professional, legal advisor, or medical professional for advice tailored to your specific situation. Review the official policy documents from SafetyWing or any other insurance provider carefully before making any decisions.