Getting Paid in Dollars as a Digital Nomad in Mexico: Where the FX Margin Goes
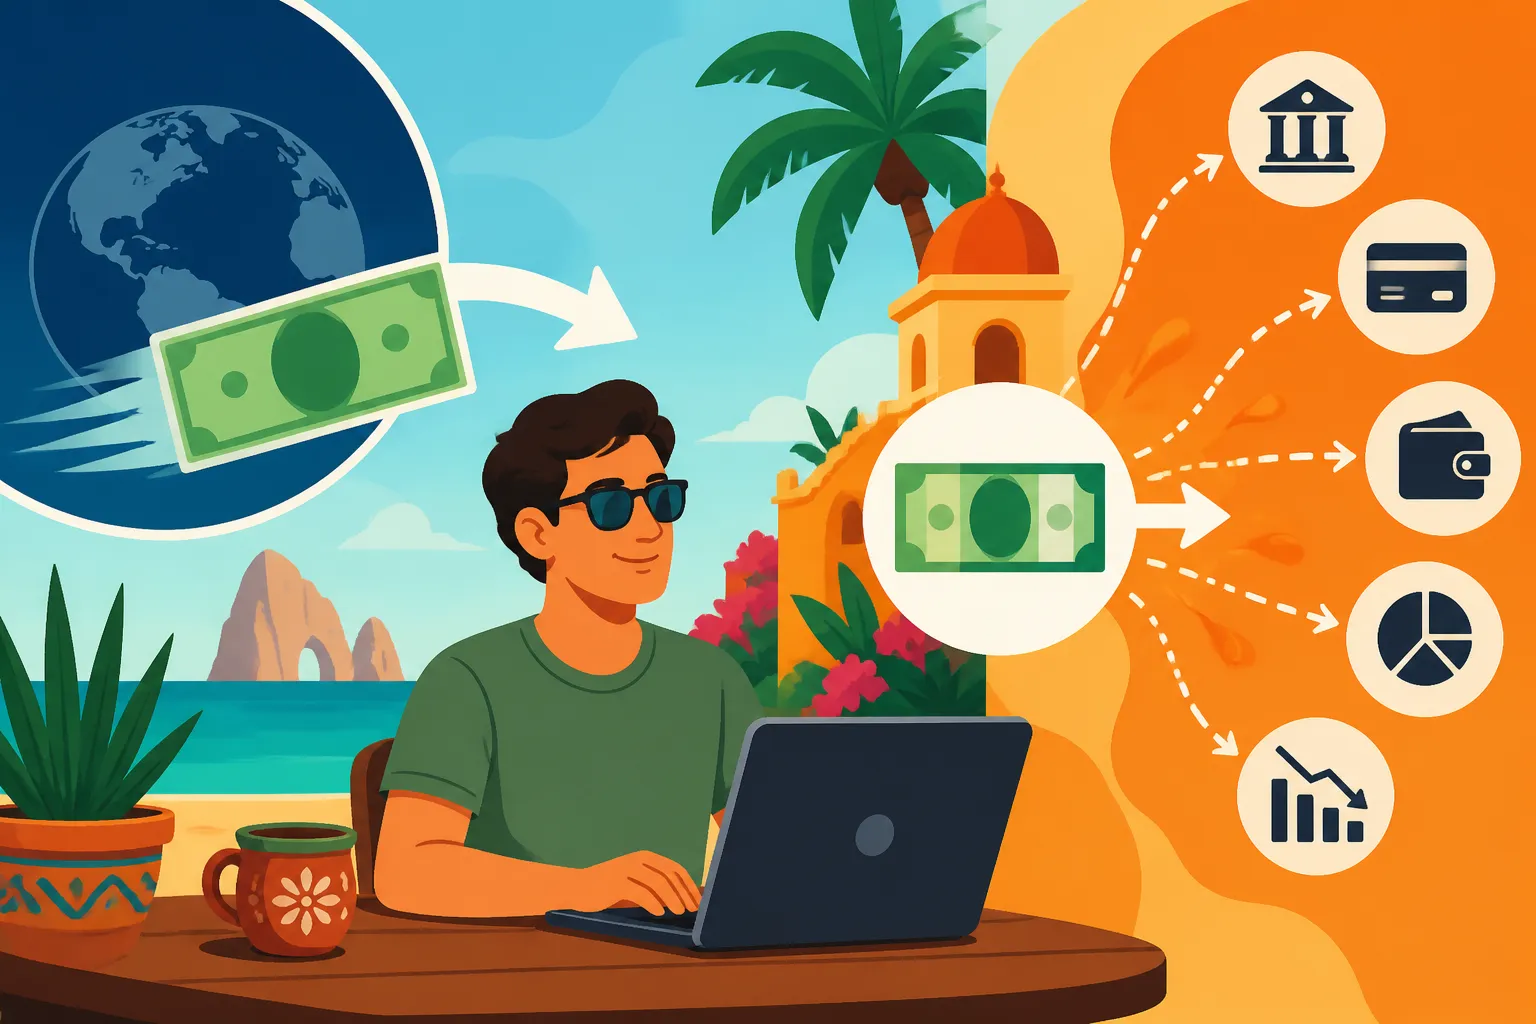
Ah, the digital nomad life in Mexico! It's a dream for so many of us, isn't it? Earning those sweet dollars or euros while living the good life here, stretching your money further than back home. But then reality hits, usually around payday, when you realize that a significant chunk of your hard-earned cash seems to vanish into thin air between your client's bank account and your Mexican one. This guide is all about understanding where that money goes and, more importantly, how to stop those sneaky foreign exchange (FX) margins from eating into your income, with a special focus on making Wise your financial superpower here.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
The Digital Nomad Dream vs. The Currency Reality
When you first start contemplating the move to Mexico as a digital nomad, the allure is undeniable. You’re often earning a salary or client fees in a stronger currency, like the US dollar, while your cost of living is significantly lower in pesos. On paper, it looks like a foolproof plan for financial freedom and a higher quality of life. You envision quaint cafes, bustling markets, and evenings spent enjoying delicious street food, all paid for with the comfortable buffer of your foreign earnings.
The Allure of Earning in Dollars While Living in Mexico
There's a real psychological comfort in earning in dollars, especially when you're living in a country like Mexico where the local currency, the peso, can fluctuate. The idea is that your purchasing power remains strong, insulated from local economic shifts, and that you'll always have a stable base. Many digital nomads assume that as long as they get paid in USD, the conversion process will be a minor detail, almost an afterthought. The dream is to simply receive your funds, convert them to pesos whenever you need, and enjoy the substantial savings compared to living in your home country.
This feeling of financial security is often a primary driver for choosing the digital nomad lifestyle in Mexico. You might be making what feels like a modest income in USD, but when you look at the potential for a richer, less stressful life here, it suddenly becomes very attractive. From renting a beautiful apartment to eating out regularly, the prospect of making your income go further is a powerful motivator.
The Silent Erosion: Why Your Dollars Don't Stretch as Far
However, many expats quickly discover that the dream of unhindered financial flow from dollars to pesos hits a snag. That "minor detail" of currency conversion quickly becomes a major pain point. It's not always obvious, and that's precisely why it's so frustrating. You'll see the amount your client sends, and then the amount that lands in your Mexican bank account, and something just doesn't add up. You might scrutinize transaction fees, thinking those are the culprits, but often, the real thief is much more insidious: the foreign exchange (FX) margin.
This silent erosion happens when your bank or payment service provides you with an exchange rate that is significantly worse than the actual market rate. They don't always disclose this as a "fee" in the traditional sense; instead, they embed their profit margin directly into the exchange rate. What you thought was going to be a simple conversion ends up costing you hundreds, sometimes thousands, of dollars over a year, depending on how much you're moving. It's a frustrating realization that your hard-earned money is slipping away without a clear explanation, and it makes that expat budget feel a lot tighter than you initially calculated.
Understanding Foreign Exchange (FX) Margins: The Hidden Cost
This is where the rubber meets the road for digital nomads in Mexico. The concept of FX margin isn't something most people think about daily, but for those of us living abroad and receiving international payments, it's crucial. It’s the difference between transparency and being nickel-and-dimed without even knowing it.
What Exactly is the FX Margin?
Simply put, the FX margin is the profit built into the exchange rate offered by a bank or a money transfer service. Imagine there's a "mid-market rate" – the true, real-time rate at which currencies are bought and sold on the global market. Think of it like the average price you'd see on Reuters or Google if you looked up the USD to MXN rate. This is the rate financial institutions use when trading among themselves.
When a traditional bank or many payment processors convert your USD to MXN, they don't give you this mid-market rate. Instead, they offer you a slightly worse rate – let's say they buy your USD for fewer pesos than the mid-market rate, or they sell you pesos for more USD. The difference between the rate they offer you and the actual mid-market rate is their profit, their "margin." It's not a separate line item called "FX margin fee" on your statement; it’s baked right into the conversion itself. This can be a few cents per dollar, but those cents add up very, very quickly when you're converting your entire salary or large client payments every month.
How Traditional Banks and Payment Processors Hide Fees
Traditional banks and many older payment processors have perfected the art of making you think you're getting a good deal, or at least a transparent one. They'll advertise "zero transfer fees" or "no commission," which sounds fantastic. You might think, "Great, my client sends $1,000, and I only pay the transfer fee to get it here." But this is often a smokescreen for the real money-maker: the inflated exchange rate.
For instance, your bank might tell you they'll convert your USD to MXN with "no fees," but then give you an exchange rate that's 2-3% worse than the actual market rate. On a $2,000 transfer, that's $40-$60 that simply disappears without a specific fee listed. These seemingly small differences accumulate significantly over time. When you're consistently converting hundreds or thousands of dollars each month, you could be losing a substantial amount of your income just to these hidden margins. Services like PayPal, while convenient for quick transactions, are notorious for offering some of the worst exchange rates, often taking a hefty bite out of your money in this way. Many platforms also employ tiered pricing, where the fee structure changes based on the amount you send, further complicating the process of calculating your true cost.
Common Methods Expats Use (and Their Downsides)
It's natural to try to find the easiest, most familiar ways to get your money into Mexico. Many digital nomads start with what they know, using banking systems and services they've always relied on. However, these methods, while seemingly straightforward, often come with a hidden price tag that slowly chips away at your earnings.
Receiving Payments Directly to a US/Canadian Bank Account
This is perhaps the most common starting point for many digital nomads. It feels safe and familiar. Your clients or employer are likely in your home country, so it makes sense for them to pay you directly into your existing bank account there. You then figure you'll just transfer it to Mexico when you need it.
The immediate pros are clear: it's what you know, your clients don't have to change anything, and the money lands in an account you trust. However, the cons are significant. When you initiate an international transfer from your US or Canadian bank to your Mexican bank, you're hit with multiple layers of costs. Firstly, there's often an outgoing wire transfer fee from your home bank, which can range from $25 to $50 per transaction. Secondly, your Mexican bank might charge an incoming wire transfer fee. But the biggest hit comes from the exchange rate the banks offer. Both the sending and receiving banks will typically use their own unfavorable exchange rates, widening the FX margin and reducing the amount of pesos you ultimately receive. These transfers can also be surprisingly slow, sometimes taking several business days, which isn't ideal when you're waiting on funds for rent or daily expenses. For more on managing your financial infrastructure, you might find this guide helpful: Do You Need a Mexican Bank Account or Can You Rely on Your Home Bank?.
Using Services like PayPal or Western Union
For smaller, more frequent payments, or for quick cash needs, services like PayPal and Western Union are often considered. They're undeniably convenient and widely recognized, especially if you need to send or receive money quickly from individuals rather than large companies.
The convenience, however, often comes at a steep price. PayPal is notorious for its poor exchange rates, often taking a spread that's several percentage points worse than the mid-market rate, in addition to transaction fees. If your client pays you via PayPal, you'll incur fees on the incoming payment, and then another hit on the exchange rate when you transfer it out to your Mexican bank. Western Union, while excellent for urgent cash pick-ups, also operates with very wide FX margins and higher fees, making it an expensive option for regular income. Limits on transfer amounts can also be a challenge for digital nomads receiving substantial monthly payments. While useful for specific situations, relying on these services for your primary income stream will see a large chunk of your earnings vanish. To truly understand your options for moving money, check out Using PayPal, Wise, or Western Union: Comparing Money Transfer Options.
Mexican Bank Accounts with Dollar Holdings
Some Mexican banks, particularly those geared towards businesses or high-net-worth individuals, offer the option to open accounts that can hold US dollars. This sounds like a perfect solution initially: receive dollars, hold dollars, and convert only when you need pesos, seemingly avoiding multiple conversions and some fees.
While this can mitigate the immediate conversion hit, it's not without its drawbacks. These accounts are often more complex to open, sometimes requiring a higher initial deposit or minimum balance, which can be challenging for newer digital nomads. Not all Mexican banks offer this service, and those that do might have specific residency or income requirements. Even with a dollar-denominated account, when you eventually need pesos for daily expenses – and you absolutely will – you're still at the mercy of the bank's exchange rate at the time of conversion. These internal bank exchange rates can still carry significant FX margins, similar to what you'd find with international wire transfers. Furthermore, these accounts often come with their own set of maintenance fees, and the process for converting funds to pesos for daily spending can sometimes be clunky. Exploring options within the Mexican banking system, including newer digital banks, can be beneficial; perhaps this guide on Mexican Fintech and Digital Banks (Nu, Klar, and More) could shed some light.
Wise: Your Hero for Maximizing Dollar Earnings in Mexico
After navigating the murky waters of hidden FX margins and costly transfers, many of us expats eventually discover a financial superhero: Wise (formerly TransferWise). This service has revolutionized how digital nomads and expats manage their international money, cutting through the red tape and opaque fee structures that traditional banks thrive on. For anyone earning in dollars and living in Mexico, Wise isn't just an option; it's often the smartest financial decision you'll make.
How Wise Works for Digital Nomads
At its core, Wise offers a multi-currency account that is a game-changer for digital nomads. Instead of just sending money between banks, Wise provides you with local bank details for several countries, including the US (ACH routing number and account number), the UK, Europe, Canada, and more. This means your clients in the US can pay you directly into your Wise USD account as if you had a local US bank account. No international wire fees, no complex routing.
The magic happens when you need to convert those dollars into Mexican pesos. Wise commits to using the real mid-market exchange rate – the one you see on Google. Their fee structure is incredibly transparent: a small, upfront fee that is clearly stated before you confirm any transfer. This fee is usually a fraction of what you’d lose in hidden FX margins with traditional banks or other services. You get to hold your money in multiple currencies, switch it when the rate is favorable, and send it to your local Mexican bank account (like Banamex, BBVA, or Banorte) when you need it. This combination of local receiving details, the true exchange rate, and transparent fees makes Wise an invaluable tool for maximizing your income in Mexico.
Step-by-Step: Receiving USD and Converting to MXN with Wise
Let's walk through exactly how you, as a digital nomad, can leverage Wise to ensure you're getting the most pesos for your dollars. It’s remarkably straightforward once you’re set up.
- Open a Wise Account and Set Up Your USD Balance: First, you'll need to create an account on the Wise website or app. Once registered, you'll want to "open a balance" in USD. Wise will then provide you with unique US bank account details – an account number and an ACH routing number. These are legitimate details that your US-based clients or employer can use.
- Share Your Wise USD Details with Clients: Instead of giving your US personal bank account details, provide your clients with your Wise USD account details. They can then pay you via direct deposit (ACH) just as they would any other US-based vendor or employee. This usually means no fees for them, and certainly no international wire fees.
- Receive Payment into Your Wise Account: The money will land in your Wise USD balance. You'll get a notification, and you can see your funds instantly. Because it’s treated as a local US transfer, it’s often much faster than an international wire.
- Initiate the Conversion to MXN: When you're ready to use your money in Mexico, open the Wise app or website. You'll choose to convert your USD balance to MXN. Wise will immediately show you the exact mid-market exchange rate and the small, transparent fee. You'll see exactly how many pesos you will receive. No surprises, no hidden margins.
- Send to Your Mexican Bank Account: Once converted, you can then send these pesos directly to your local Mexican bank account. This transfer is treated as a local Mexican SPEI transfer, meaning it’s typically very fast – often arriving within minutes, or at most a few hours. This makes managing your local expenses incredibly efficient. For a deeper dive into the mechanics of cross-border transfers, you might find Sending Money To and From Mexico: Transfers and Fees quite helpful.
This streamlined process, centered around Wise, eliminates several layers of fees and poor exchange rates, ensuring you retain more of your income.
Beyond Just Good Rates: Other Wise Benefits
While the stellar exchange rates and transparent fees are the primary draw for Wise, its utility extends far beyond just converting your digital nomad income. It’s built with the international lifestyle in mind, offering a suite of features that simplify cross-border financial management.
One major benefit is the Wise debit card. This card allows you to spend directly from any currency balance you hold, meaning you can spend USD when traveling back home, or use it for online purchases in other currencies, all while benefiting from the mid-market rate. If you spend pesos, it automatically converts from your available balance at the best rate, avoiding foreign transaction fees often charged by traditional bank cards.
The speed and reliability of transfers are also a huge plus. Knowing that your money will typically arrive in your Mexican bank account within minutes or hours, rather than days, offers immense peace of mind. This is particularly important for rent payments or other time-sensitive bills. Furthermore, for those managing international clients or subscriptions, Wise allows you to make payments in various currencies, often at a better rate than your traditional bank would offer. It truly simplifies your financial life, making it easy to pay for software in Euros, receive payments in USD, and spend in MXN, all from one intuitive platform. Wise understands the needs of digital nomads, offering a financial tool that truly supports an international lifestyle.
Best Practices for Digital Nomads Managing Money in Mexico
Navigating the financial landscape as a digital nomad in Mexico requires a bit of strategy beyond just choosing the right transfer service. It’s about building a robust financial system that protects your earnings, simplifies your daily life, and keeps you compliant with local regulations.
Diversifying Your Banking Strategy
While services like Wise are fantastic for international transfers and currency conversion, it's generally a smart move to have a diversified banking strategy. This typically means having a local Mexican bank account alongside your international accounts. A Mexican bank account is essential for everyday transactions here. Rent payments, local utility bills, and many smaller businesses in Mexico operate primarily with local bank transfers (SPEI) or cash. While your Wise card is great, having a local account for direct deposits from Wise and for managing day-to-day spending is a huge convenience.
Consider popular Mexican banks like BBVA Bancomer, Banorte, or Santander. They all offer different benefits, and having an account with one of them makes you feel much more integrated into the local economy. You'll find it easier to pay bills at OXXO, receive money from local friends, and generally handle your finances without constant international transfers. This guide on How to Open a Bank Account in Mexico as a Foreigner can provide all the details you need to get set up. Maintaining a balance in your Mexican bank account that covers your immediate expenses (e.g., two to four weeks' worth) means you're not constantly initiating transfers and can benefit from converting larger amounts from Wise when the exchange rate is favorable.
Budgeting and Tracking FX Rates
Effective budgeting becomes even more critical when you're dealing with multiple currencies. Your income might be stable in USD, but its value in pesos fluctuates daily. This means your "peso budget" needs to be somewhat flexible.
Start by creating a detailed budget in MXN for all your local expenses: rent, groceries, utilities, transportation, and leisure. Know your fixed monthly costs in pesos. Then, monitor the USD to MXN exchange rate regularly. Tools like Google Finance, XE.com, or the Wise app itself provide real-time rates. By understanding the typical range and current trends, you can make informed decisions about when to convert larger chunks of your USD income to MXN. For example, if the peso weakens against the dollar, your dollars will buy more pesos, making it a good time to convert. Conversely, if the peso strengthens, you might hold off on converting more than you immediately need. This proactive approach can save you a significant amount over time. For more general financial planning, this resource on How to Track Spending and Budget in Pesos in Mexico can be a lifesaver.
Tax Implications of Earning Foreign Income
This is a big one, and often overlooked by new digital nomads. Just because you're earning in dollars from clients outside Mexico doesn't mean you're exempt from Mexican taxes once you become a tax resident here. Generally, if you spend more than 183 days in Mexico in a calendar year, you are considered a tax resident and are liable to pay taxes on your worldwide income in Mexico.
It’s crucial to understand your obligations and potentially register with the SAT (Servicio de Administración Tributaria), Mexico’s tax authority, to obtain an RFC (Registro Federal de Contribuyentes). You'll likely need to file monthly declarations and an annual tax return. Ignoring these requirements can lead to penalties down the line. While it might seem daunting, there are tax regimes like RESICO (Régimen Simplificado de Confianza) that can simplify things for freelancers and small business owners, often with lower tax rates. It is highly recommended to consult with a Mexican accountant (contador) who specializes in foreign residents. They can help you navigate the system, ensure compliance, and potentially leverage double taxation treaties if applicable. This article on Declaring Foreign Income in Mexico: Tax Rules for Expats is an excellent starting point, as is understanding The RFC and SAT: Mexico's Tax System for Foreigners. Don't let tax planning become an afterthought; it's a fundamental part of responsible digital nomad life.
Comparing Your Options: Where Your Money Really Goes
To truly grasp the value Wise brings to digital nomads in Mexico, let's look at a side-by-side comparison of how various methods handle your money, particularly focusing on that elusive FX margin.
| Feature | Traditional Banks (US/Canada to Mexico) | PayPal / Western Union | Mexican Bank (USD account) | Wise (Multi-Currency Account) |
|---|---|---|---|---|
| Exchange Rate | Bank's unfavorable rate | Significantly unfavorable rate | Bank's unfavorable rate (for MXN) | Mid-market rate (real rate) |
| Hidden FX Margin | High (embedded in rate) | Very High (embedded in rate) | High (when converting to MXN) | Very Low / Transparent |
| Transfer Fees | Outgoing wire (high), incoming wire | Variable, often high per transaction | Account maintenance, conversion fees | Small, transparent flat fee |
| Speed to Mexico (MXN) | Several business days | Varies (can be quick for cash, slower for bank) | Immediate (if already MXN) / Days (for USD to MXN) | Minutes to hours (local SPEI) |
| Transparency | Low (fees and rate often unclear) | Low (rate is often hidden) | Moderate (rate only clear at conversion) | High (all fees & rate upfront) |
| Receiving USD from client | Direct deposit to home bank | Via PayPal account / WU pickup | Direct deposit (if offered & setup) | Local US account details provided |
| Debit Card for Spending | Home bank card (FX fees abroad) | Limited/Expensive | Local MXN card (no FX for MXN) | Multi-currency card (best FX rate) |
As you can clearly see from this table, while other services might offer perceived convenience or familiar branding, Wise stands out for its commitment to the mid-market exchange rate and radical transparency. This isn't just a minor difference; it's a fundamental shift that puts more of your actual earnings into your pocket, rather than into the hidden margins of financial institutions. For digital nomads in Mexico, where every peso counts and financial flexibility is key, choosing Wise can make a significant difference to your monthly budget and overall financial well-being.
Disclaimer
Please remember that I am a lifestyle blogger and not a financial advisor. The information provided in this guide is for general informational purposes only and does not constitute financial, legal, or tax advice. While I strive to provide accurate and up-to-date information, financial regulations and market conditions in Mexico can change. It is always recommended to consult with a qualified financial planner, tax professional, or immigration lawyer for advice tailored to your specific situation before making any significant financial decisions.