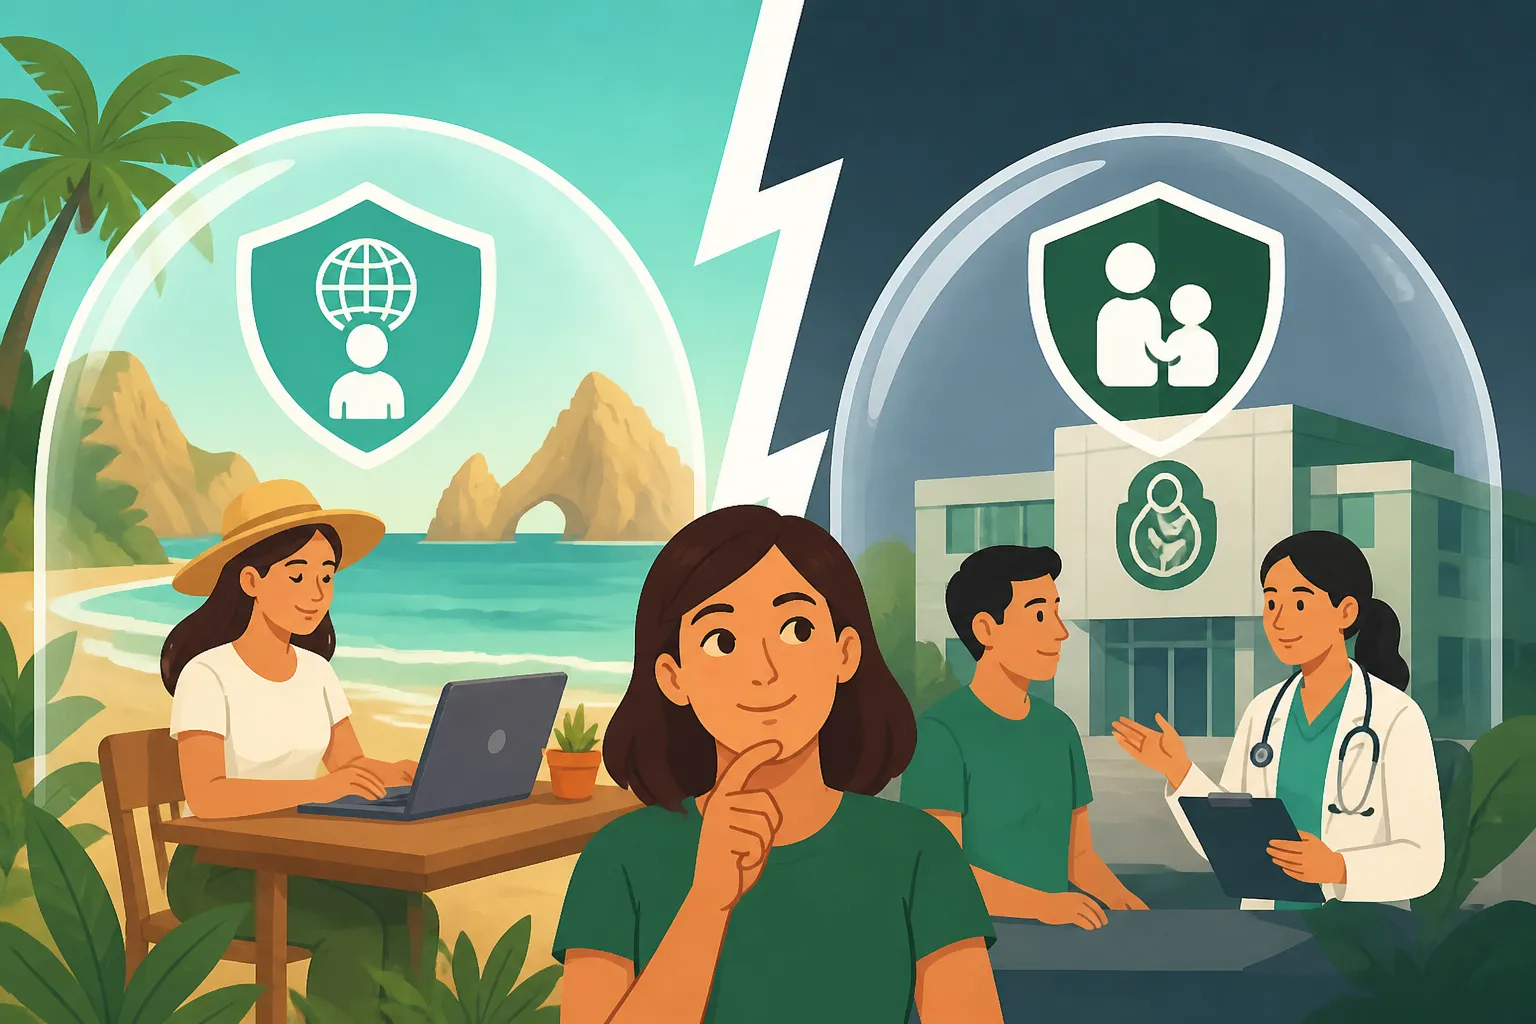
Nomad Insurance vs Voluntary IMSS: Two Very Different Safety Nets
When you first move to Mexico, or even if you’ve been here a while, figuring out your healthcare can feel like wading through quicksand. One of the biggest head-scratchers for many foreign residents is trying to understand the different health coverage options, especially when comparing something like a flexible nomad insurance plan to the more traditional, local public system. This guide is here to untangle the complexities of Nomad Insurance versus Voluntary IMSS, helping you pinpoint which safety net truly fits your unique expat life in Mexico.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Understanding Nomad Insurance: Your Flexible Global Safety Net
When I first arrived in Mexico, the idea of traditional health insurance felt… heavy. Like another brick in the wall of bureaucracy. That's where the concept of "nomad insurance" really started to shine for many of us who weren't quite ready to commit to a long-term, country-specific plan, or who simply needed coverage that moved with us. It’s a game-changer for those who embrace a more fluid lifestyle.
The Basics of Travel and Nomad Insurance
Think of nomad insurance as a safety net designed for the globally-minded individual. Unlike typical travel insurance, which is often short-term and mainly covers trip interruptions or acute emergencies, nomad insurance is built for longer stays abroad and often includes a broader range of medical coverage. It’s tailored for those of us living outside our home country for extended periods, providing a sense of security no matter where we are in the world, or at least across a very wide geographical area.
The beauty of these plans is their flexibility. Many traditional health insurance policies are very geographically restrictive – they cover you only in your home country, or only within Mexico. But if you're someone who might spend a few months exploring the Yucatán, then pop over to Guatemala for a bit, or even head back home for a quick visit, a conventional plan can fall short. Nomad insurance recognizes this reality, offering continuous coverage that isn't tied down to a single location. It's truly for the international resident who doesn't fit neatly into a "tourist" or "permanent resident" box when it comes to healthcare.
How SafetyWing Caters to the Expat Lifestyle
Among the various nomad insurance providers out there, SafetyWing stands out as a popular choice for expats and digital nomads, particularly in places like Mexico. They’ve really honed in on the specific needs of our community, understanding that most of us aren't here to stay forever in one spot, but we also aren't just here for a two-week vacation. Their flagship product, Nomad Insurance, offers medical coverage as well as travel benefits, which is a fantastic two-for-one. It means if you get sick or have an accident, you’re covered, but it also helps if your luggage gets lost or your trip gets interrupted. This dual-purpose coverage is what makes it so appealing.
What makes SafetyWing so practical for those of us living in Mexico is its rolling subscription model. You don't sign up for a fixed year, feeling trapped if your plans change. Instead, it works much like a monthly subscription service, allowing you to start and stop your coverage as needed. This flexibility is incredibly valuable when your life abroad is often in flux. Plus, they offer coverage for incidental home country visits, which is a huge relief. If you need to fly back to see family or for a specific medical appointment, you often retain some level of coverage back home for a short period, avoiding that awkward gap in protection. It's these kinds of details that show they understand the expat journey.
Key Features and Benefits: Global Coverage and Ease of Use
The primary draw of a robust nomad insurance like SafetyWing is its truly global reach. While your primary residence might be Mexico, life here often involves travel. Whether it's a weekend trip to a nearby Pueblo Mágico, a longer journey down to Oaxaca, or an international flight for work or pleasure, your coverage generally goes with you. This worldwide coverage (often excluding the U.S., or with limited U.S. coverage as an add-on, due to the high costs there) is a significant advantage over many local plans. Imagine falling ill while exploring the Mayan ruins in Chiapas; your nomad insurance is there.
Another major benefit is the straightforward claims process. While no insurance claim is ever "fun," SafetyWing has designed theirs to be as user-friendly as possible, often involving online submissions. For many of us who already navigate enough paperwork in Spanish, having a streamlined, English-language claims process is a huge weight off our shoulders. This ease of use, combined with the comprehensive coverage for both unexpected medical issues and travel-related mishaps (like travel delays or lost checked luggage), makes it an incredibly appealing choice for those who value convenience and peace of mind on the move. When you're constantly adapting to a new culture and language, having one less administrative headache is priceless.
Understanding Voluntary IMSS: Mexico's Public Health Safety Net
On the other side of the coin, we have the Mexican social security system, known as IMSS (Instituto Mexicano del Seguro Social). For many of us who are settling down, buying property, or truly integrating into Mexican society, IMSS becomes a very real and often appealing option. It's the public healthcare system, and while it might not offer the plush comforts of private hospitals, it's a robust system that forms the backbone of healthcare for millions of Mexicans.
The Ins and Outs of Mexico's Public Health System (IMSS)
IMSS is a vast, government-run social security institution that provides healthcare, pensions, and other social benefits to Mexican workers and their families. As an expat, you might interact with the "Voluntary Regime" of IMSS, which allows non-working residents (like retirees or those working remotely for foreign companies) to opt into the system. It’s an integral part of the country’s social fabric, providing essential medical care from basic doctor visits to specialized surgeries and even medication. Think of it as Mexico’s answer to national health services found in many other countries.
However, it's crucial to manage expectations. The IMSS system can sometimes be slow, and facilities vary wildly in quality and modernity. While many hospitals are perfectly competent, you might encounter longer wait times for appointments and procedures, especially for non-emergencies. The system is designed to serve a massive population, so efficiency isn’t always its strongest suit. But for the incredibly low cost, it offers a truly comprehensive package of care, including pharmaceuticals, which can be a massive financial relief. It's a trade-off many of us seriously consider.
Eligibility and Enrollment for Foreign Residents
The process to enroll in voluntary IMSS has become more straightforward for foreign residents in recent years, but it still requires some bureaucratic navigation, as does most everything in Mexico! To qualify, you generally need to be a temporary or permanent resident of Mexico. A tourist visa won’t cut it. Once you have your residency card, you can begin the enrollment process, which typically involves providing your residency document, passport, CURP (Clave Única de Registro de Población), proof of address, and undergoing a basic medical examination. Yes, they do a check-up, and this leads us to an important point: Does IMSS Cover Pre-Existing Conditions in Mexico? In short, sometimes, but there are often waiting periods, or certain conditions may be excluded initially.
The annual fee for voluntary IMSS is determined by your age. Younger individuals pay less, and the cost increases as you get older. This makes it particularly attractive for retirees, as even at higher age brackets, the annual fee is significantly less than many private insurance plans. You pay the annual sum upfront, and then you’re covered for the next 12 months. For a detailed walkthrough, check out our guide on How to Enroll in IMSS: Step-by-Step Guide for Foreign Residents. Once enrolled, you are assigned to a local clínica familiar (family clinic) where you will receive most of your primary care. It’s a deep dive into the local system, and it demands patience, but the rewards can be substantial.
Benefits and Limitations of IMSS Coverage for Expats
The biggest benefit of IMSS, hands down, is its cost-effectiveness and comprehensive nature once you're in the system. For a relatively low annual fee, you get access to medical consultations, specialist visits, hospital stays, surgeries, and a wide array of medications, often completely free at the point of service. This includes even complex treatments, which can be a huge relief, especially for those Managing Chronic Illness in Mexico: Access to Medication and Specialists. It’s a full-service public healthcare system.
However, IMSS is not without its limitations. The primary challenge for many expats is the language barrier; most doctors and staff will speak only Spanish. While some larger cities might have bilingual staff, it's not a guarantee, which can be daunting during a health crisis. Our guide on Overcoming Language Barriers at the Doctor: Tips for Expats can be a lifesaver here. Another significant point is that IMSS generally only covers you within Mexico, and specifically within the IMSS network. It’s not portable if you plan to travel outside the country. Moreover, while emergency care is always available, elective procedures and specialist appointments can involve considerable wait times. For many, these trade-offs are acceptable given the immense savings and the sense of truly belonging to the local system.
Key Differences: Coverage, Cost, and Flexibility
Now that we’ve looked at each option individually, let’s talk turkey. The real decision comes down to understanding the stark differences in how these two safety nets operate, and more importantly, how they might serve your specific needs as an expat in Mexico. There’s no one-size-fits-all answer here, which can be frustrating, but we’re going to break it down.
Scope of Medical Services: What's Covered Where?
When comparing coverage, it's like apples and oranges, but both are fruit. Nomad insurance like SafetyWing is designed with a broad brush. It covers acute illnesses, accidents, and often offers some basic preventative care, but its strength lies in covering unexpected emergencies globally. If you break an arm in Thailand, or get a nasty stomach bug in Peru, you’re generally covered, and you can seek treatment at almost any private facility and submit a claim. This flexibility in choosing your provider, often even in Mexico, is a huge plus for those who prioritize rapid, English-speaking care in private hospitals.
IMSS, on the other hand, is a deeply integrated, all-encompassing system within Mexico. It covers a vast range of services, from vaccinations and check-ups to chronic disease management, maternity care, and even organ transplants. The catch? You must use IMSS facilities and doctors. You can't just walk into a private hospital or clinic and expect IMSS to cover it. The quality of care within IMSS can be excellent, but the experience is very different from private healthcare. This includes access to medication, where Pharmacies in Mexico: How to Get Medications (OTC vs Prescription) is often handled differently if you're an IMSS patient versus a private patient. The care is there, but it’s within their network and according to their procedures.
Financial Commitments: Premiums, Deductibles, and Out-of-Pocket
This is where the financial calculators often come out! Nomad insurance plans like SafetyWing typically have a monthly or annual premium, similar to private insurance, along with a deductible you pay out-of-pocket before the insurance kicks in. The cost can vary based on your age and chosen coverage limits, but generally, it's competitive for international coverage. However, the true benefit is in avoiding catastrophic costs for emergencies or serious illnesses while traveling. For instance, if you get appendicitis and need emergency surgery, the insurance would cover the vast majority after your deductible. Remember, too, that for those who don't have health insurance, Healthcare Costs in Mexico: Doctor Visits, Hospital Stays, and Surgery Expenses can add up very quickly.
Voluntary IMSS is typically a single, upfront annual payment. Once that’s paid, most services, medications, and treatments within the IMSS network are completely free. There are no deductibles or co-pays for services received at an IMSS facility. This can be an incredible financial relief, especially for older expats or those with ongoing health concerns, as there are no surprises once your annual fee is covered. The downside? If you choose to seek private care for any reason – perhaps for faster service, a specific specialist, or an English-speaking doctor – IMSS will not cover those costs, and you’ll be paying entirely out of pocket for that private visit. This is why some expats opt for a "belt and suspenders" approach, having both.
Geographic Reach and Portability
This is perhaps the most significant differentiator. Nomad insurance is built for portability. If your lifestyle involves frequent travel, even just within Mexico or to neighboring countries, a plan like SafetyWing keeps you covered. It moves with you, providing continuous protection wherever you are in your covered region (which is often worldwide, with specific limitations like the U.S. or your home country). This is invaluable for digital nomads, temporary residents, or anyone with wanderlust.
IMSS, conversely, is deeply rooted in Mexico. Your coverage is strictly within the national IMSS system. It's fantastic if you're planning to stay put and truly integrate, but it offers zero coverage if you step across the border. If you travel back to your home country or take a vacation to, say, Costa Rica, you are completely uninsured for medical emergencies through IMSS. This often means needing additional Travel Insurance vs Local Insurance: Do Expats Need Both? if you rely solely on IMSS for your primary healthcare while living in Mexico. This lack of portability is a critical factor for many to consider.
Here's a quick comparison table to help visualize these differences:
| Feature | Nomad Insurance (e.g., SafetyWing) | Voluntary IMSS (Mexico) |
|---|---|---|
| Primary Focus | Travel medical emergencies, acute illness, global portability | Comprehensive public healthcare within Mexico |
| Coverage Area | Worldwide (often with U.S. restrictions/add-ons) | Exclusively within Mexico (IMSS network) |
| Cost Structure | Monthly/Annual premium + Deductible | Annual fee (age-based), typically no deductibles/co-pays |
| Provider Choice | Flexible, often any private hospital/clinic | Restricted to IMSS clinics and hospitals |
| Enrollment Basis | Online, subscription model, flexible start/stop | In-person at IMSS office, annual commitment, requires residency |
| Pre-existing Conditions | Often covered after waiting period or with specific limitations | Often covered after waiting periods; some may be excluded |
| Language Barrier | Claims typically in English, access to English-speaking docs | Services primarily in Spanish, limited English support |
| Waiting Times | Generally fast access to private care | Can be long for specialists/elective procedures |
| Ideal For | Digital nomads, frequent travelers, temporary residents | Settled residents, retirees, long-term integrators |
Who Benefits Most from Each Option?
It's clear that these two options serve different needs. The "best" choice really depends on your lifestyle, your health, your travel habits, and how deeply you plan to root yourself in Mexican society. Let's dig into who each solution is truly built for.
For the Digital Nomad and Frequent Traveler
If your passport is well-worn, your laptop is your office, and the idea of being tied to one clinic fills you with dread, then a nomad insurance plan like SafetyWing is almost certainly your champion. This is especially true for digital nomads who might be working remotely for a company back home and don't technically "work" in Mexico. You're not looking to get deeply embedded in the local social security system, but you absolutely need solid medical coverage. The flexibility of a monthly subscription with SafetyWing, where you can pause or resume coverage as your plans shift, is unparalleled.
Think about it: you’re exploring Mexico City one month, then heading to the beaches of Tulum, and next year you might decide to spend a season in Lisbon. Your health coverage needs to keep up. Nomad insurance means you have peace of mind that if you get sick or have an accident, you can access private care in most countries without jumping through hoops. For the temporary resident who might eventually consider Permanent Residency Explained: A Complete Guide (2026) but isn't quite there yet, or for those on a Temporary Resident Visa: Comprehensive Guide for Expats (2026 Update) with a flexible lifestyle, SafetyWing offers essential freedom and security.
For the Settled Expat Seeking Local Integration
Now, if your dream is to plant roots, embrace the local culture fully, and perhaps retire in Mexico, then voluntary IMSS becomes a very attractive proposition. This system is designed for long-term residents who intend to stay in Mexico indefinitely and want to access the same public healthcare system as millions of Mexicans. It's particularly beneficial for retirees on a fixed income, as the annual fee, even for older age groups, is incredibly affordable compared to private options, and it offers extensive coverage for age-related health issues.
Choosing IMSS means you are truly integrating. You’ll have a local doctor at your clínica familiar, you’ll get your medications from the IMSS pharmacy, and you’ll learn how the system works. It’s a commitment to the local way of life, language, and sometimes, patience. But for those who embrace this integration, the financial security of comprehensive, low-cost healthcare without worrying about deductibles or co-pays is a huge relief. It's a way to feel truly connected to the country you've chosen to call home, offering a solid safety net for all your medical needs within its borders. Our general guide on Healthcare in Mexico: Complete Guide for Expats (Public vs Private) really dives into the intricacies of this decision.
Hybrid Approach: When to Consider Both
What if you're somewhere in the middle? Perhaps you're a retiree who wants the affordability of IMSS for daily care but also frequently travels back home or takes international trips. Or maybe you're a digital nomad but plan to stay in Mexico for years and want the local security but also value access to faster private care for certain situations. In these cases, a hybrid approach might be the smartest move.
Many expats choose to enroll in voluntary IMSS for their primary, low-cost, comprehensive care within Mexico, especially for long-term conditions or routine check-ups. Then, they layer on a separate travel insurance policy or a more basic nomad insurance plan (like SafetyWing, which offers both medical and travel benefits) specifically for trips outside of Mexico. This gives you the best of both worlds: the affordability and deep coverage of the local public system for your daily life here, and the global portability and flexibility of nomad insurance for when you’re on the move. It’s a sensible strategy that balances cost, coverage, and peace of mind for an expat lifestyle that often defies simple categories.
Making the Right Choice for Your Expat Journey
Deciding on health coverage is deeply personal, and there's a lot riding on it. It’s not just about money; it’s about your well-being, your peace of mind, and how you envision your life unfolding in Mexico. Let’s look at how to navigate this important decision.
Assessing Your Personal Health Needs and Travel Plans
Before you even look at a policy, take a good, honest look at your health. Are you generally fit and healthy, only needing coverage for the unexpected? Or do you have pre-existing conditions that require regular medication or specialist care? Your personal health profile will heavily influence which option makes more sense. If you have complex medical needs, understanding the waiting periods and exclusions of both IMSS and private plans (including nomad insurance) is paramount. Pre-Existing Conditions: Will Mexican Health Insurance Cover You? is a must-read if this applies to you.
Next, consider your travel habits. Are you a true digital nomad, hopping countries every few months? Or do you foresee yourself mostly staying within Mexico, with perhaps one annual trip back home? If you travel extensively, the global coverage of SafetyWing will be incredibly appealing. If your travel is minimal, the local focus of IMSS might be sufficient, supplemented by separate travel insurance for those occasional trips. This isn't just about fun vacations; it's about being prepared for a medical emergency no matter where you are.
Navigating the Enrollment Process for Each
The enrollment experience itself is a world apart. Signing up for SafetyWing, or most nomad insurance plans, is typically an online process. You answer a few questions, provide payment details, and voilà, you're covered, often within minutes. It’s designed for modern convenience and minimal bureaucracy, which is a breath of fresh air for many of us who dread Mexican paperwork.
Enrolling in Voluntary IMSS, however, is a journey. It requires in-person visits to an IMSS office, gathering various documents, and undergoing a medical exam. It’s a commitment of time and patience. You’ll need your official residency card, your CURP, proof of address, and other identity documents. You might encounter language barriers and long waits. But once you’re through it, that annual payment locks you into a year of robust, local care. Our detailed guide on Public Healthcare in Mexico: IMSS and IMSS Bienestar Explained for Expats can help you brace for the experience and prepare thoroughly.
Beyond the Basics: What Else to Consider
Beyond the immediate concerns of coverage and cost, think about your overall comfort level. Are you comfortable navigating a public health system that operates primarily in Spanish, potentially with long waits and a more austere environment than you're used to? Or do you prioritize the ability to choose your own private doctor and hospital, even if it means a higher premium? This is a very personal preference.
Also, consider your family. Do you have children or a spouse who will also need coverage? Some nomad insurance plans offer family coverage, and IMSS extends to your dependents once you're enrolled. The logistics of healthcare for children, for example, might influence your decision, as finding a good pediatrician and reliable care is paramount for expat parents. Finally, always be aware of the specific terms and conditions of any policy you consider, especially regarding maximum benefits, exclusions, and how claims are processed. No one wants an unpleasant surprise when they're already feeling unwell.
Ultimately, whether you lean towards the flexible, global reach of a nomad insurance like SafetyWing or the comprehensive, local integration of Voluntary IMSS, the most important thing is that you have some form of health coverage. Don't leave your well-being to chance in your Mexican adventure.
Disclaimer
Please remember that I am an expat blogger and not a licensed financial, legal, or medical professional. The information provided in this guide is based on personal experience, general knowledge, and publicly available information about healthcare and insurance in Mexico as of the publication date. Regulations and policies can change, and individual circumstances vary greatly. It is always recommended to consult with a qualified insurance agent, financial advisor, or immigration lawyer in Mexico to get personalized advice tailored to your specific situation.