How to Choose Between IMSS and Private Insurance in Mexico
One of the most stressful hurdles you will face when moving to Mexico is the sudden realization that your home country's healthcare safety net is gone, replaced by a complex choice between public bureaucracy and private premiums. I remember sitting in a local coffee shop in Querétaro during my first month, staring at two drastically different quotes and feeling completely lost. This guide solves that confusion by breaking down exactly how to weigh IMSS against private insurance so you can choose the path that fits your budget and your health needs.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
Understanding the Core Differences
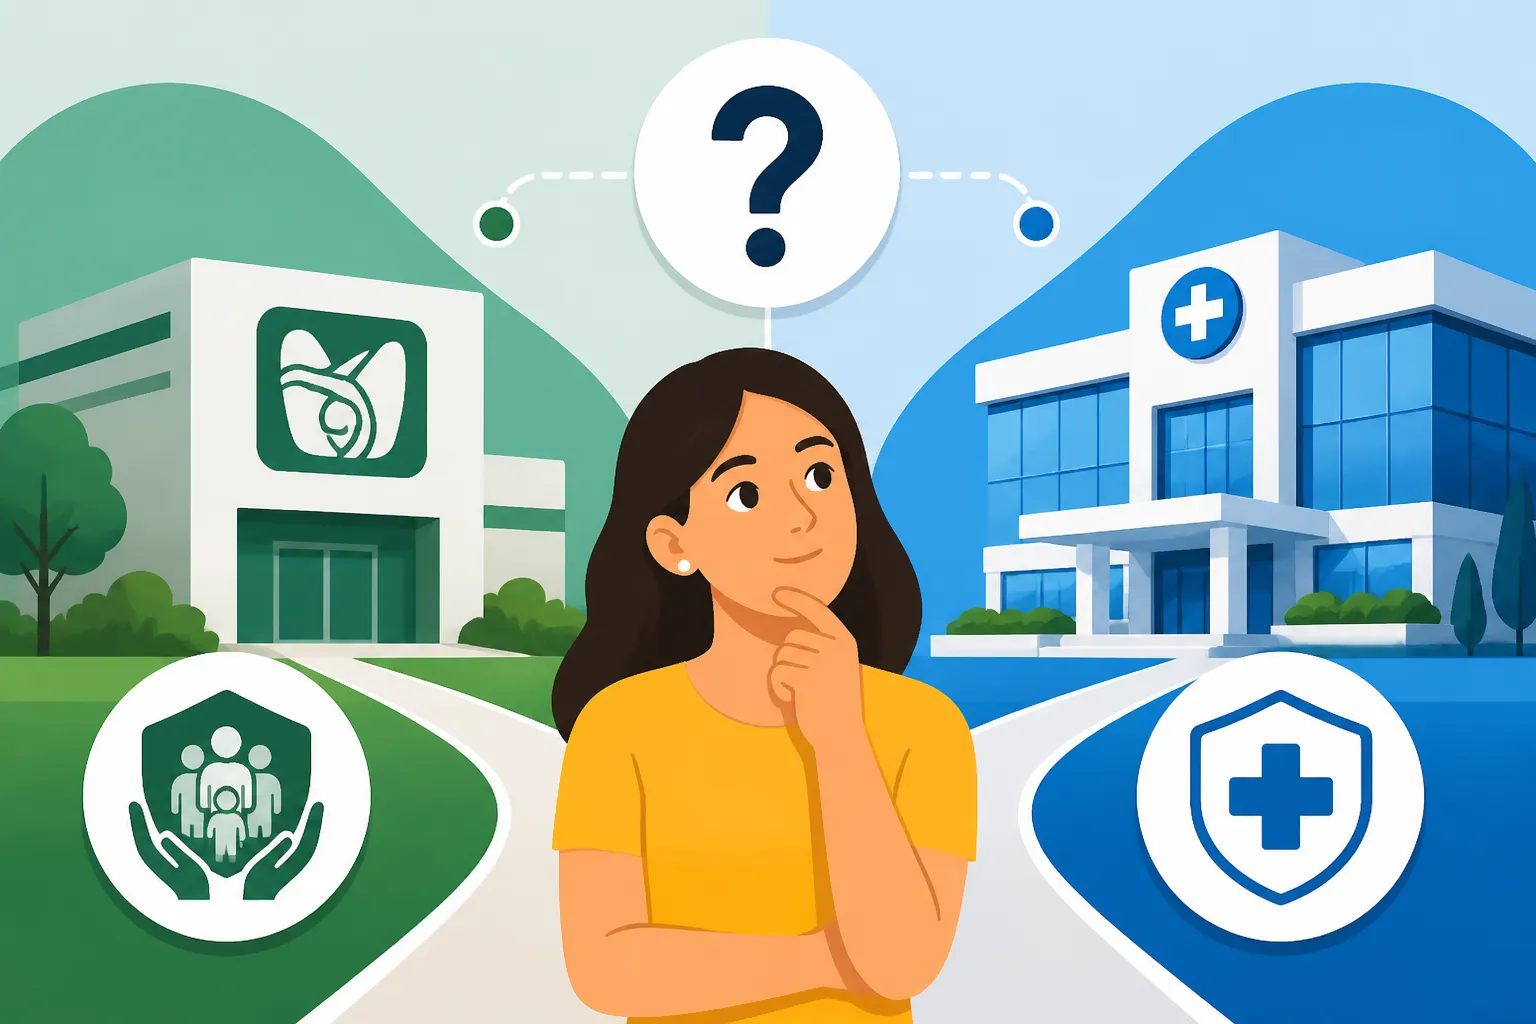
When we talk about healthcare in Mexico, we are really talking about two parallel universes that rarely intersect. On one side, you have the Instituto Mexicano del Seguro Social (IMSS), which is the massive public healthcare system that covers millions of Mexican workers and residents. On the other side, you have the private sector, which includes high-end hospitals that feel more like luxury hotels than medical facilities. Choosing between them isn't just about the cost of the premium; it’s about the value you place on your time, your comfort, and your peace of mind.
To get a baseline understanding of how the whole country operates, I highly recommend reading through the Healthcare in Mexico: Complete Guide for Expats (Public vs Private). It’s important to realize that IMSS is an all-encompassing system. If you are a member, your consultations, surgeries, and even your medications are theoretically covered for one annual fee. However, the private system functions much more like what you are likely used to in the U.S. or Canada, where you pay for a policy and then use it to access specific private doctors and hospitals.
The private system is where brands like Cigna Global often come into play for expats. Cigna Global provides the kind of comprehensive, international coverage that allows you to walk into the best hospitals in Mexico City or Guadalajara without worrying about whether the staff speaks English or if the equipment is state-of-the-art. In contrast, IMSS is a "Spanish-only" environment where the doctors are highly skilled, but the resources are often stretched thin.
The Financial Reality Comparing Costs
Let’s talk about the money, because for many retirees and digital nomads, this is where the rubber meets the road. IMSS is undeniably cheaper. If you are a legal resident, you can apply for voluntary enrollment. The cost is based on your age, but even for those in their 60s or 70s, the annual fee is usually less than $1,000 USD per year. If you are trying to figure out your specific budget, you should check out the latest breakdown on How Much Does Voluntary IMSS Cost per Year? to see where you fall on the sliding scale.
Private insurance is a different beast entirely. A local "Gastos Médicos Mayores" (Major Medical Expenses) policy from a Mexican insurer can range from $1,500 to $5,000 USD per year depending on your age and health history. If you opt for an international plan like Cigna Global, the price may be higher, but you gain the ability to seek treatment back in your home country or anywhere else in the world.
For the younger crowd or those who are just "testing the waters" in Mexico, there are more flexible options. I often see digital nomads using SafetyWing because it offers a bridge between travel insurance and full-scale health insurance. SafetyWing is particularly useful because it’s a subscription model, which is much easier on the wallet than a massive annual payout for a private Mexican policy while you are still waiting for your residency to be finalized.
Comparison of Key Features
| Feature | IMSS (Public) | Private Insurance |
|---|---|---|
| Annual Cost | Low (approx. $600 – $1,100 USD) | Moderate to High ($1,500 – $10,000+) |
| Wait Times | Can be long for non-emergencies | Very short / Immediate |
| Language | Strictly Spanish | English-speaking staff common |
| Medication | Included (if in stock) | Out-of-pocket or reimbursed |
| Pre-existing Conditions | Strict waiting periods/Exclusions | Often excluded or requires higher premium |
| Doctor Choice | Assigned to you | You choose your specialist |
Quality of Care and Accessibility
One thing I learned the hard way is that "cheap" doesn't always mean "available." While IMSS has some of the best surgeons in Latin America, getting in to see them is a test of patience. You start at your local clinic (UMF), and you must be referred upward through the system. This can take weeks or months. If you want a deeper look at this dynamic, Wait Times in Mexico: Public vs Private Healthcare Services gives a very realistic picture of what to expect when you're sitting in a waiting room for four hours just to get a blood test.
Private care is the polar opposite. You can usually see a top-tier specialist the same day or the next day. In private hospitals, the technology is often newer, and the patient-to-nurse ratio is much lower. This is why many expats view Health Insurance in Mexico: How Expats Can Get Coverage (2027) as a non-negotiable part of their relocation plan. If you have a heart condition or a chronic illness that requires frequent monitoring, the convenience of private care is worth every penny of the premium.
However, do not count IMSS out for emergencies. In many smaller towns, the IMSS hospital might actually be better equipped for a major trauma than a tiny private clinic. This is why Medical Emergencies in Mexico: What Expats Should Know and Prepare is a vital read. You need to know which hospital is the "trauma center" in your specific city, regardless of whether you have a private card in your wallet.
The Hurdle of Pre-existing Conditions
This is the "gotcha" that catches many expats off guard. If you have a pre-existing condition, like diabetes or high blood pressure, choosing between IMSS and private insurance becomes much more complicated. Private insurers in Mexico are notorious for excluding anything you had before you signed the contract. Some might cover it after a two-year "waiting period," while others will simply never cover it.
IMSS also has its own rules. There is a list of "pre-existing conditions" that will outright prevent you from joining the voluntary scheme. Even if you are allowed to join, there are specific waiting periods (some up to 24 months) for things like cancer treatment or major orthopedic surgery. You must read Does IMSS Cover Pre-Existing Conditions in Mexico? before you make any final decisions. I have seen people cancel their home-country insurance thinking IMSS would cover their insulin on day one, only to find themselves paying out of pocket for months.
If you have complex health needs, an international provider like Cigna Global might be your only path to getting comprehensive coverage that actually addresses your history, albeit at a significantly higher cost. They are often more experienced in underwriting expats with manageable chronic conditions than local Mexican companies.
Language and Navigation
I cannot emphasize this enough: IMSS is a Spanish-language world. From the security guard at the gate to the specialist in the office, you will be expected to communicate in Spanish. If your Spanish is currently limited to "Hola" and "Una cerveza, por favor," the IMSS system will be a nightmare for you unless you bring a translator to every single appointment.
Private hospitals, especially in expat hubs like Puerto Vallarta, San Miguel de Allende, or Ajijic, almost always have bilingual staff. Many of the doctors in the private sector actually did their residency in the U.S. or Europe. If you are worried about the language barrier, check out the guide on Finding English-Speaking Doctors and Specialists in Mexico. It will save you a massive amount of anxiety during a medical crisis.
Navigating the physical buildings is also different. When you are Navigating Hospitals and Clinics in Mexico: An Expat’s Guide to Medical Care, you will find that private hospitals operate much like business centers. You can find everything in one building. In the IMSS system, you might have to go to one building for a consultation, another across town for a lab test, and a third for your pharmacy needs. It is a logistically heavy system that requires a lot of "tramites" (paperwork).
Hybrid Strategies The Best of Both Worlds
Most veteran expats I know don't actually choose one or the other. They use a hybrid strategy. This is the most "pro" move you can make.
The strategy usually looks like this: You enroll in IMSS to have a permanent safety net for catastrophic issues, very expensive long-term medications, and to satisfy the "permanent residency" mindset. Then, you carry a high-deductible private policy—perhaps something like SafetyWing for basic mishaps or a local major medical policy—to handle surgeries, specialist visits, and hospital stays where you want comfort and speed.
By having both, you ensure that if a private hospital bill exceeds your policy limit (which can happen with very long ICU stays), you can theoretically be transferred to the IMSS system for long-term recovery. It’s a "belt and suspenders" approach that protects your life and your life savings. For those who are just starting out, Choosing Private Health Insurance: Local Mexican Plans vs International Coverage provides a great roadmap for setting up this dual-layer protection.
How to Get Started with Your Choice
If you decide to go the IMSS route, the first step is getting your residency in order. You cannot join as a tourist. Once you have your card, you need to follow the How to Enroll in IMSS as a Foreign Resident in Mexico process precisely. This involves a trip to the sub-delegación office with your CURP, proof of address, and your passport.
If you decide to go private, start by getting quotes from at least three different sources. Look at a local insurer like GNP or AXA, and compare them against an international heavy-hitter like Cigna Global. If you are a digital nomad or still in your first few months of "scouting" Mexico, a subscription with SafetyWing is a fantastic way to stay covered while you navigate the more permanent bureaucratic requirements of the local systems.
The right choice depends on your age, your health, and your tolerance for sitting in plastic chairs. I personally keep a private policy because I value the ability to call my doctor on WhatsApp and get an appointment the next morning. However, I know many happy expats who swear by the IMSS system and the community feel of their local clinics. Take your time, do the math, and remember that your health is the one thing you can't afford to get wrong in your new Mexican life.
Disclaimer
The information provided in this article is for informational purposes only and does not constitute medical, legal, or financial advice. Healthcare laws, insurance policy terms, and IMSS regulations in Mexico are subject to frequent changes. Always consult with a licensed insurance broker, an immigration attorney, or a medical professional before making decisions regarding your healthcare coverage in Mexico.