Residency by Investment in Mexico: Financial Solvency vs Property Ownership Paths
Many would-be residents hit the same wall. You own a condo in Puerto Vallarta, or you have a healthy brokerage account, and the consulate checklist still leaves you unsure which proof counts. This guide compares the two main investment-style paths to Mexican residency, financial solvency and property ownership, so you can pick the route that fits your money and paperwork.
Disclosure: This post may contain affiliate links. We may earn a commission at no extra cost to you if you make a purchase through these links. Read full disclosure.
How Residency by Investment Actually Works in Mexico
Mexico does not run a “golden visa” in the European sense. There is no single program where you write a cheque and receive a card. Mexican immigration law instead asks one question: can you show economic independence? The investment paths are different ways of answering it. You can show recurring income, accumulated savings or investments, real estate you own in Mexico, or capital placed in a Mexican business.
Each path ends in the same process. You apply at a Mexican consulate outside Mexico and get a visa sticker in your passport. You then enter Mexico and finish the process at an INM office, where the sticker is swapped for a physical resident card. That second step is called the canje. If you are new to the sequence, see How to Complete the Canje After Entering Mexico before you book flights.
The Two Paths Most Expats Weigh
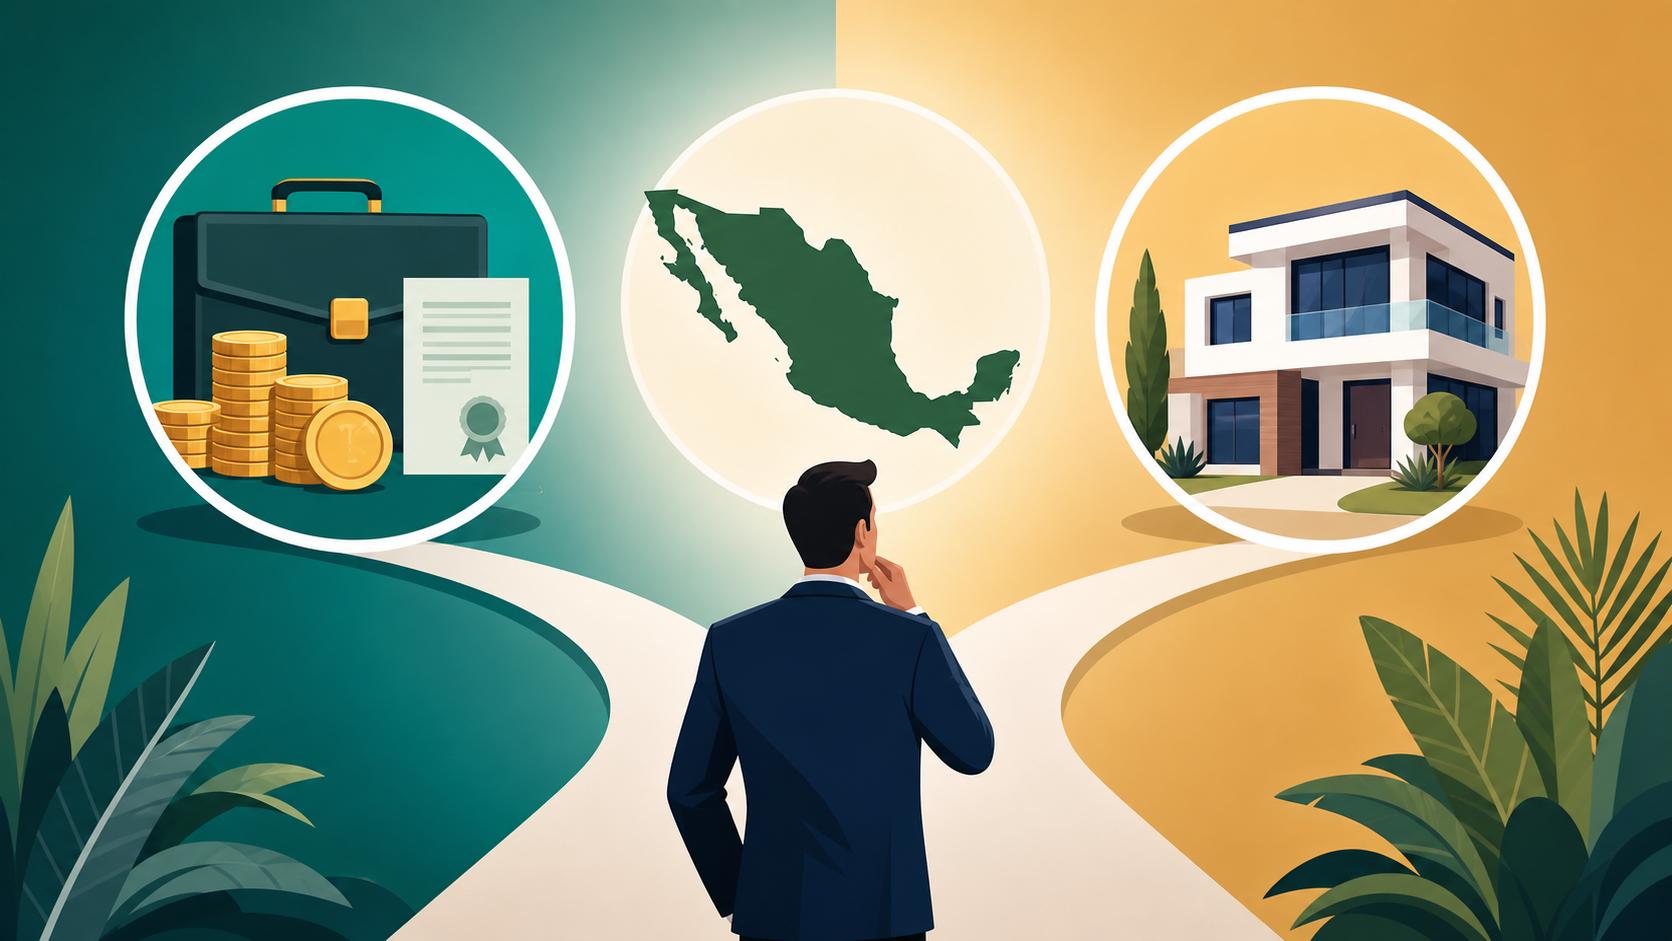
The two routes expats compare most are these:
- Financial solvency. You prove income or a savings and investment balance.
- Property ownership. You prove you hold title, or trust rights, to Mexican real estate above a set value.
A third route involves investing in a Mexican company. It suits entrepreneurs more than retirees or remote workers, and it carries its own corporate paperwork.
I watched a couple in my Spanish class in Mérida agonize over this for weeks. He had a modest pension. She had sold a business and held most of their wealth in an investment account. Their colonial house in Santiago was already bought. Each of them could, in theory, have qualified three different ways. Their real question was which route gave the least painful renewal and the cleanest path to permanent residency later.
Why the UMA Matters to Both Routes
Mexico does not set its thresholds in dollars. They are set as multiples of the UMA, the Unidad de Medida y Actualización, a reference unit that is updated periodically. Consulates convert that figure into local currency. Different consulates may round, convert, or interpret the figure slightly differently, and the result can move with exchange rates.
Do not copy a number from a forum post written by someone who applied in another city at another time. Check the current figure on the website of the specific consulate where you will apply. Our guide Understanding Mexico’s UMA: How It Determines Financial Requirements explains the mechanics. Choosing where to apply matters too, and Can I Apply for Mexican Residency at Any Consulate? Choosing the Right One covers the jurisdiction rules.
The Financial Solvency Path Explained
Financial solvency is the route most people mean when they say they “qualified on paper.” The full breakdown sits in Economic Solvency Requirements for Mexican Residency. Here is the shape of it.
Proving Income Versus Proving Savings
There are two sub-routes:
- Income. You show a steady monthly amount above the consulate’s threshold, sustained over a lookback window of several months. Pensions, Social Security, salary, and regular remote-work earnings all typically count.
- Savings and investments. You show an average balance above a much higher threshold, also over a lookback window. Bank accounts, brokerage accounts, and certain retirement accounts can qualify, but consulates vary on what they accept.
Picture Dana, a freelance designer from Oregon. Her income swings wildly. One month she bills a large project, the next she bills almost nothing. Her monthly average might clear the bar, yet a consular officer scanning twelve statements can see two near-empty months and hesitate. She may be better off with the savings route if her investment account is steady. Lumpy income is one of the most common reasons solvency applications stall.
Temporary Versus Permanent Through Solvency
Solvency can lead to either temporary or permanent residency. Permanent residency granted directly at the consulate usually requires a higher, typically pension-based income. That is why retirees so often skip temporary status altogether. Everyone else generally starts temporary and upgrades later. For that transition, see Upgrading from Temporary to Permanent Residency in Mexico: What You Need to Know.
The realistic frustration is that you prove solvency at the consulate, then often have to show similar stability again at renewal. Keep your statements organized from day one. Name your PDF files by month. You will thank yourself.
Pros and Cons of the Solvency Route
The advantages:
- It works whether or not you own anything in Mexico.
- It can lead straight to permanent residency for qualifying pensioners.
- The documents are simple: statements, a passport, the application form, and photos.
The drawbacks:
- Exchange rate swings can push a borderline applicant under the threshold between the moment you check and the day of your appointment.
- Consulates differ on whether they accept retirement accounts, joint accounts, or crypto holdings.
- You must keep the money where it is during the lookback window. Moving it right before your appointment resets the clock in the eyes of the officer.
The Property Ownership Path Explained
The property route lets you qualify for temporary residency by owning Mexican real estate whose value exceeds a threshold, again set as a UMA multiple. Our detailed explainer Qualifying for Mexican Residency by Purchasing Property (Investment Route) goes deeper. These are the parts that trip people up.
What Counts as Proof of Ownership
Consulates generally want the escritura, the notarized deed, or the fideicomiso documents if your home sits in the restricted zone near coasts and borders. If you bought through a bank trust, you hold beneficiary rights rather than direct title. Our article What Is a Fideicomiso? A Foreigner’s Trust for Owning Coastal Property explains how that structure works.
Proof of value is usually the deed value or an official appraisal, depending on the consulate.
Here is the trap I see constantly. In many Mexican purchases, the value written in the deed is lower than what the buyer actually paid. This is often done to reduce closing taxes. Imagine Mark, who paid a healthy sum for a two-bedroom in Bucerías, while the escritura records a noticeably smaller figure. The consulate looks at the deed, not his bank transfer receipts, and his property appears to fall short. Before you lean on this route, read your escritura and look at the declared value.
Temporary Only, With Strings Attached
Property ownership typically qualifies you for temporary residency, not permanent residency directly. At renewal you will generally need to show you still own the property. If you sell mid-way, you lose the basis for that status and need to switch to solvency or another route.
You also take on the running costs of ownership. Predial (property tax), condo cuotas, and fideicomiso fees all keep coming. The predial basics are in Property Taxes in Mexico: What Expats Need to Know About Predial.
Pros and Cons of the Property Route
The advantages:
- It suits people with real wealth tied up in a home but modest monthly income.
- No lookback period on bank balances is needed.
- Your home and your immigration case are anchored in the same place.
The drawbacks:
- A deed undervaluation can disqualify an otherwise wealthy owner.
- The documents are heavier: deed, trust papers, sometimes appraisals and proof of tax payments.
- It generally leads only to temporary residency.
- Your status becomes tied to an illiquid asset.
Solvency vs Property: A Side-by-Side Comparison
This table summarizes the practical differences most applicants care about.
| Factor | Financial Solvency | Property Ownership |
|---|---|---|
| Main proof | Bank, pension, or investment statements | Escritura or fideicomiso, plus valuation |
| Threshold basis | UMA multiple for income or average balance | UMA multiple for property value |
| Residency type | Temporary or, for higher pension income, permanent | Typically temporary only |
| Lookback window | Yes, several months of statements | No balance history, but ownership must be current |
| Biggest risk | Exchange rates and lumpy income | Deed value recorded below real price |
| Renewal ease | Must keep showing stability | Must still own the property |
| Best fit | Pensioners, salaried remote workers, savers | Owners with high property value and low income |
Can You Combine Both Paths?
People ask me this constantly. Generally you apply under one primary basis, but extra evidence rarely hurts if a consulate allows it. Some applicants submit solvency documents and mention property as supporting context.
Do not overload the file with irrelevant paperwork. Officers process many applications a day, and a clean, focused submission reads better. If you are unsure, call or email the consulate. Some, such as the busy offices in Phoenix, Houston, or Los Angeles, publish detailed checklists online.
A Realistic Scenario Comparison
Take two neighbors in San Miguel de Allende:
- Linda has a pension that clears the higher permanent threshold. She applies on solvency and walks out with permanent residency approval. She never renews again.
- Tom owns a beautiful house in Guadalupe but lives on irregular consulting income. He qualifies through property for temporary residency. He renews while the house stays in his name, and he plans to switch to solvency once his savings grow.
Neither path is “better.” They solve different life situations.
Step-by-Step: Preparing Your Investment-Based Application
Whichever route you choose, the preparation looks broadly similar. Here is the order that works best.
Your Document Workflow
- Pick the consulate first. You usually apply in the jurisdiction where you reside. Read that office’s current requirements page, not a generic list.
- Choose your primary basis. Decide on solvency through income, solvency through savings, or property. Do it honestly, based on which one you clear most comfortably.
- Gather the core documents. That means your passport, the visa application form, photos to the consulate’s specifications, and either your statements or your property documents.
- Check deed details if using property. Confirm the declared value, the owner names, and that the fideicomiso is in good standing with the trustee bank.
- Handle translation and legalization. Documents issued in a language other than Spanish may need translation, and some foreign public documents may need an apostille. Rules differ between the consular stage and INM in Mexico.
- Attend the consular appointment. Bring originals and copies, organized in the order the checklist lists them.
- Enter Mexico and complete the canje. You must start the canje at INM within 30 days of entering Mexico.
- Calendar your renewal. Put a reminder well before your temporary card expires.
Translations and Apostilles Without the Headache
Translation is where I wasted the most time on my own application. Consulates abroad often accept English-language bank statements. INM offices inside Mexico more commonly want Spanish versions of foreign documents such as marriage or birth certificates. Some INM offices specifically ask for a perito traductor, a translator authorized by a Mexican court.
For documents where a certified translation is accepted, many expats use RushTranslate because it is quick to order online. Confirm with your specific office first whether it will accept a certified translation from an online service or insists on a local perito. Asking costs nothing. Redoing translations costs time and money.
For apostille questions, see What is an Apostille, and Do You Need It for Mexican Immigration Documents?.
Health Coverage Alongside Your Application
Health insurance is not usually a core requirement for these visas. It still becomes urgent the moment you live here. During the months between your consular approval and getting settled, you may have no Mexican coverage at all.
Retirees and property owners who want international cover often look at Cigna Global, partly because it is designed for people living abroad long-term rather than tourists. Whatever provider you consider, check its own pages for current plan details and exclusions before you buy. Some people later add or switch to local options once residency is in place. For the immigration side of this question, read Do You Need Health Insurance for a Mexican Residency Visa?.
If you expect a hospital stay in a city like Guadalajara or Mexico City, ask any insurer you consider, including Cigna Global, whether it offers direct billing with the hospitals near your home. Many expats only discover this gap when the bill arrives.
When to Bring in Professional Help
Plenty of people do this alone. The property route can justify a facilitator or lawyer, especially when deeds, trusts, or co-ownership with a spouse complicate things.
Watch for these red flags:
- Your deed value looks low next to what you paid.
- Your property is co-owned with someone who is not applying.
- You hold assets in a corporate entity.
Our comparison Do You Need an Immigration Lawyer for Mexico? DIY vs Professional Help lays out when paying for help actually saves money.
The emotional truth is that this process feels opaque because it partly is. Officers have discretion, offices interpret rules differently, and requirements get updated. Prepare a clean file, pick the path you clear most comfortably rather than barely, and keep copies of everything. That approach gets most people through, whether their wealth sits in a brokerage account or in a house with a view of the Bay of Banderas.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.